
What brokers send
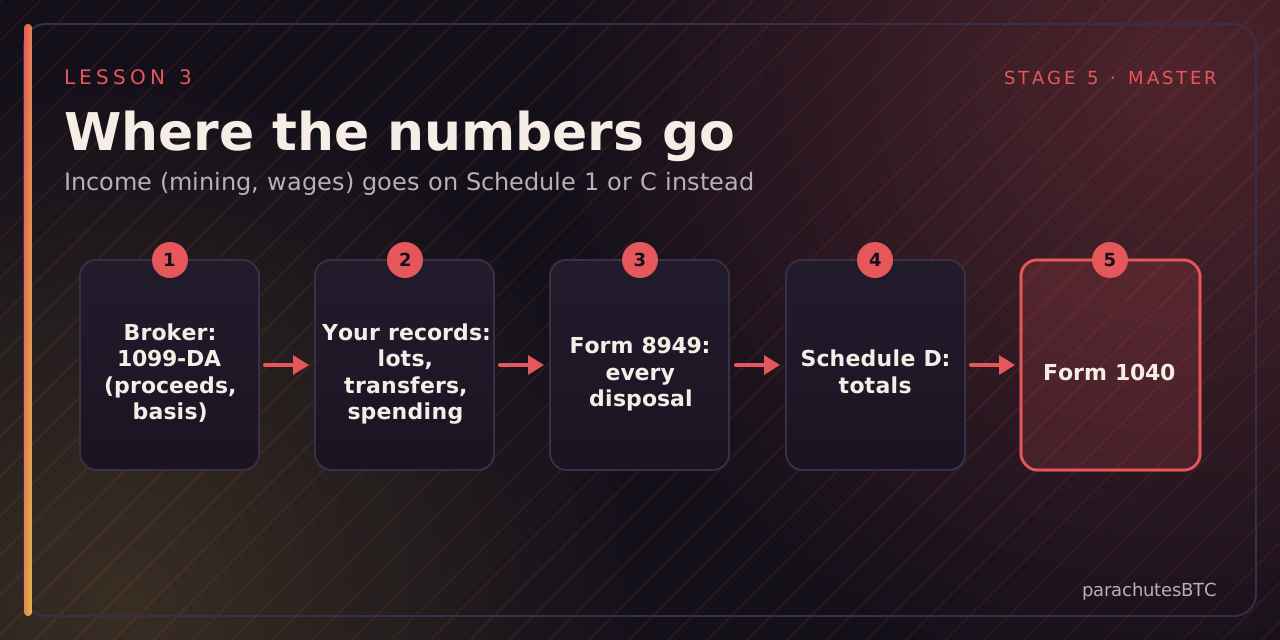
From the 2025 tax year, US brokers issue Form 1099-DA for digital asset sales, with gross proceeds; from 2026 they also report cost basis for coins bought on their platform. If you moved coins in from elsewhere, the broker does not know your basis and may report it as zero or missing, which overstates your gain unless you correct it with your own records.
Where it goes
- Form 8949: one line per disposal: date acquired, date sold, proceeds, basis, gain or loss. Short-term and long-term in separate sections. A year of DCA plus a few sales can be hundreds of lines; software exports them.
- Schedule D: totals from 8949, netting gains and losses.
- Form 1040: the net result, plus the question on page one asking whether you received, sold or exchanged digital assets. Answer honestly; it is asked under penalty of perjury.
- Income: mining, rewards and payments go on Schedule 1 (other income) or Schedule C (if a business), not on 8949. The value received becomes the basis of those coins.
Deadlines
15 April for most; 15 June for citizens abroad; extensions to 15 October on request by 15 April. Estimated taxes may be due quarterly if gains are large.
Fixing mistakes
Amend prior years with Form 1040-X. Correcting a missed report voluntarily is far cheaper than being found later.
Software
Tax software connects to exchanges and wallets, matches transfers, and produces the 8949. It is only as good as the completeness of what you connect; a wallet you forgot shows up as missing basis. Review its output before filing.