
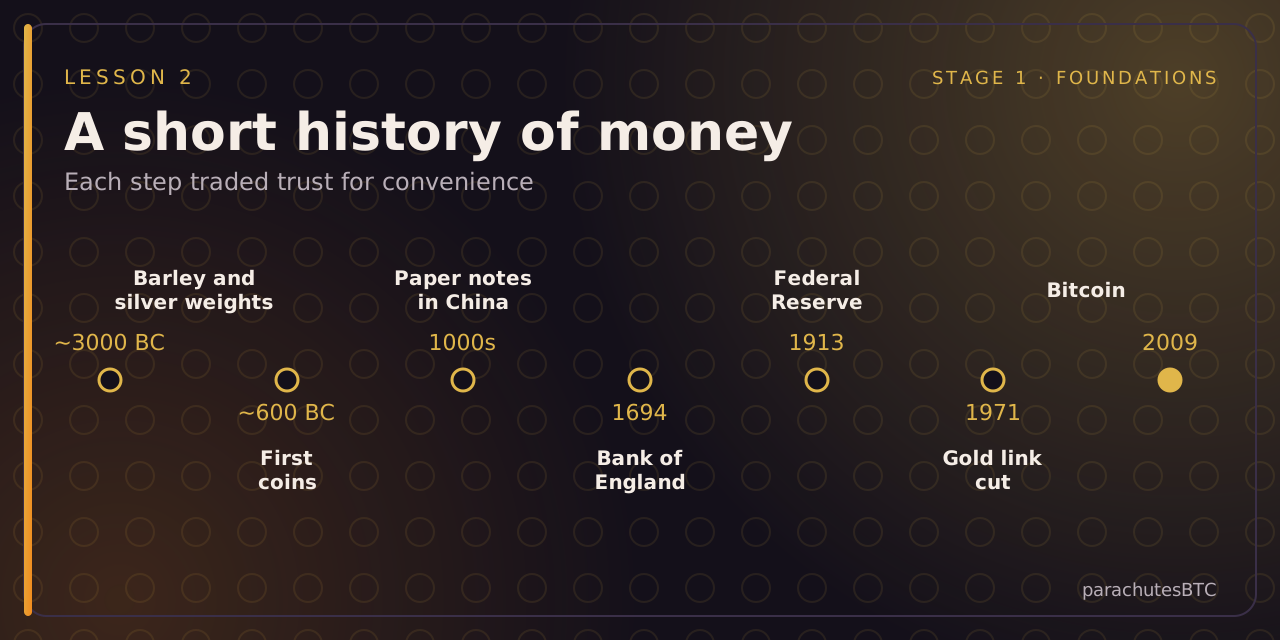
Money was not invented by a king. It emerged. Carl Menger showed in 1892 that in any market, people drift toward holding the good that is easiest to sell on later. Over time one good wins, and that good becomes money.
What won, and why
- Collectibles and commodities. Shells, beads, salt, cattle. Useful, but easy to find more of or hard to divide.
- Silver and gold. Scarce, durable, divisible, recognisable. For about 2,500 years, precious metal was the money that lasted.
- Coins. Stamped by rulers so weight and purity did not need checking each time. Also the first opportunity for rulers to cheat: Rome steadily cut the silver in the denarius until it was nearly worthless.
- Paper notes. Began as receipts for metal held by a goldsmith or bank. Lighter to carry, and a new question: is the metal really there?
- Bank money. Today most money is a number in a bank's database. Physical cash is a small fraction.
The pattern
Each step made money more convenient and moved trust to a new party: the mint, the bank, the central bank, the government. Convenience is real. So is the risk that the trusted party changes the rules.
~2,500 years
that precious metal served as money before fiat became the global norm in 1971
Tap a card to flip it.
CHECK YOURSELF
pick an answer for each question
Next
Money today is called fiat. Lesson 3 explains what that word means and who controls it.