
Businesses holding bitcoin
Since 2025, US accounting rules (ASU 2023-08) require companies to carry bitcoin at fair value, with changes through earnings each period, replacing the old impairment-only rule that could only mark down. Taxes still follow the property rules: a business realises gains on disposal. Accepting bitcoin for sales is revenue at the value received, which becomes basis. Paying employees or contractors in bitcoin is wages or payments at value, with the usual withholding and reporting.
Mining
Mined coins are ordinary income at their value when received, and that value is their basis. Equipment and electricity are business expenses if mining is a business (depreciation applies to hardware), hobby income if not. Selling mined coins later is a capital gain or loss from that basis. Businesses may owe self-employment tax.
Records
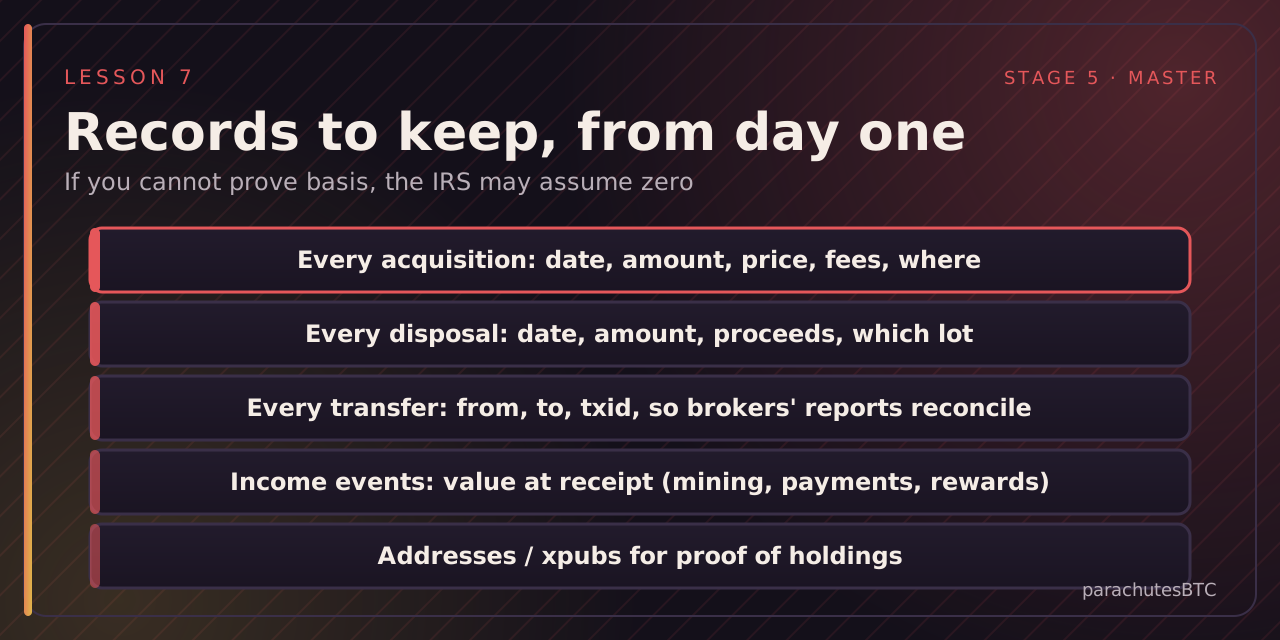
An audit asks two questions: what did you dispose of, and what was its basis. Keep:
- Acquisitions: date, amount, price, fees, platform.
- Disposals: date, amount, proceeds, and which lot, if using specific identification.
- Transfers: both sides and the transaction ID, so a broker's "sale" that was really a withdrawal can be explained.
- Income: value at receipt for every mining payout, reward or payment.
- Proof of holdings: addresses or xpubs (kept privately) that tie the records to the chain.
If you cannot prove basis, the IRS may treat it as zero and tax the whole amount as gain. Software helps; exports kept in your own files help more, because platforms close.
The rule under everything
Nothing in this course replaces a professional who knows your situation and this year's law. The purpose was to make you a better client and a better record-keeper, which is most of the battle.